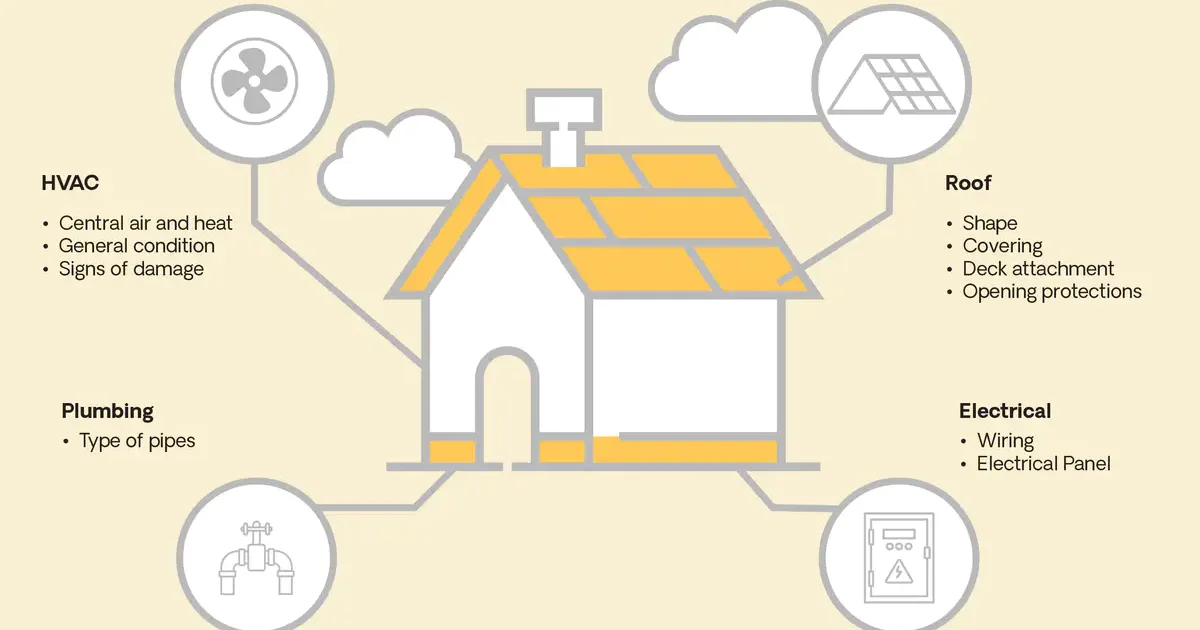
Your insurance carrier wants to know four things about an older house: the roof, the electrical, the plumbing, and the HVAC. A four-point inspection answers all four in the format an underwriter expects, so your policy does not stall.
Schedule This Inspection
The findings that stop coverage here are predictable. Hail has worked over most roofs in the region at least once, and a roof that was patched instead of replaced shows it. Older San Antonio and Austin neighborhoods still hold Federal Pacific Stab-Lok and Zinsco panels, along with cloth-wrapped and aluminum branch wiring. Polybutylene supply lines from the eighties are still in service in plenty of houses. And hard Hill Country water takes years off a water heater, so age on the label rarely matches condition in the closet.
A four-point inspection is not a home inspection. It is a focused report on four systems, written for an insurance underwriter rather than for a buyer, and it answers one question: is this house an acceptable risk to insure?
The four points are the roof, the electrical system, the plumbing system, and the HVAC system. For each one the report documents age, material or type, visible condition, and any active deficiency. Carriers ask for this on older homes, typically once a house passes twenty-five or thirty years, and increasingly on any home where the roof age is unclear.
In Central Texas the findings that stop a policy are fairly consistent. Roofs worked over by hail and never properly replaced. Cloth-wrapped or aluminum branch wiring in houses from the fifties and sixties. Federal Pacific Stab-Lok and Zinsco panels, which are still out there across older San Antonio and Austin neighborhoods. Polybutylene supply lines from the eighties. Water heaters well past their service life, which hard Hill Country water shortens considerably.
Knowing about any of that before you submit the report to your carrier is the entire point. Jeremy inspects and documents what is there, and the report goes out within 24 hours so it does not hold up your binder.
Jeremy covers Austin, San Antonio, and the Hill Country in between. Pick your area to see what inspections here actually involve.
A home inspection covers the whole house and is written for you. A four-point covers four systems and is written for an insurance underwriter. If you are buying, you usually want the full inspection, and the four-point alongside it if your carrier asks for one.
Carriers use it to price and accept risk on older homes. Once a house passes roughly twenty-five or thirty years, most carriers will not write or renew without current documentation on the roof, wiring, plumbing, and HVAC.
You find out before the underwriter does, which is the useful part. Most deficiencies can be corrected and re-documented. Knowing about a Stab-Lok panel or a twenty-year-old water heater in advance is far better than having a binder fall through at closing.
Within 24 hours of the inspection, usually the same day, with photo documentation of everything noted. Four-points are frequently time-sensitive, so they do not sit.
Serving Austin & San Antonio. Veteran-owned, detail-driven, zero conflicts of interest.